Home Insurance in
California
Affordable homeowners insurance in California with coverage for your home, belongings, and liability. Get reliable protection against fire, theft, and unexpected damage with fast quotes and competitive rates.
Coverage Options
Dwelling Coverage
Protects your home’s structure in California against fire, weather, and covered damage.
Personal Property Coverage
Covers your belongings like furniture, electronics, and valuables inside your home.
Liability Protection
Provides liability coverage if someone is injured on your property or you’re legally responsible.
Loss of Use Coverage
Pays for temporary housing and living expenses if your home becomes uninhabitable.
Other Structures Coverage
Protects detached structures like garages, fences, and sheds on your property.
Who This Is For
Homeowners
Protection for your primary residence against damage, theft, and liability risks.
Landlords
Coverage for rental properties, protecting your investment and liability exposure.
Renters
Affordable coverage for belongings and personal liability.
Home Insurance
We provide affordable home insurance in California with flexible coverage options to protect your property and assets. Whether you need basic homeowners insurance or extended coverage for high value homes, we help you find the best rates from top rated carriers. Our policies cover your home, personal belongings, and liability, giving you peace of mind against unexpected risks. Even homeowners in high risk areas, including fire zones or difficult to insure properties, can find reliable coverage through our network.
- Home Insurance in California for All Property Types
- Coverage for Fire, Liability & Property Protection
- Fast Quotes with Competitive Rates from Top Carriers
Get Your Free Quote
California Homeowners Insurance
Your home is one of your most important investments. The right homeowners insurance policy can help protect the building, your personal belongings and your financial security when a covered loss occurs.
Caspian Coverage Insurance Services helps homeowners throughout California compare available coverage, understand policy limits and deductibles, and identify important coverage gaps before purchasing or renewing a policy.
What Does Homeowners Insurance Cover?
A homeowners insurance policy combines several types of protection. The exact coverage depends on the insurance company, policy form, selected limits, endorsements and exclusions.
Dwelling Coverage
Helps repair or rebuild the structure of your home after damage caused by a covered loss. Your dwelling limit should be based primarily on the estimated cost of rebuilding—not simply the property’s purchase price or current market value.
Other Structures Coverage
Provides coverage for qualifying structures that are separated from the home, such as a detached garage, fence, gazebo or storage shed.
Personal Property Coverage
Helps replace furniture, clothing, electronics and other belongings damaged or stolen because of a covered loss. Jewelry, collectibles, artwork and certain other valuable items may have special limits and may require additional scheduled coverage.
Loss of Use Coverage
May help pay additional living expenses when a covered loss makes your home temporarily uninhabitable. This can include qualifying increases in hotel, rental housing and meal expenses while repairs are completed.
Personal Liability Coverage
May help protect you when you or a covered household member is legally responsible for bodily injury or property damage to another person. It may also help pay covered legal defense expenses.
Medical Payments to Others
May help pay minor medical expenses when a guest is injured on your property, regardless of fault, subject to the policy’s terms and limits.
Home Insurance Options for Different Property Owners
Homeowners
Coverage for an owner-occupied primary or secondary residence, including the home, personal belongings, additional living expenses and personal liability.
Condominium Owners
Coverage designed for the interior of a condo unit, personal property, loss assessments, improvements and personal liability. The condominium association’s master policy generally covers different portions of the property.
Landlords and Rental Property Owners
Insurance for residential properties rented to others. A landlord policy differs from a standard homeowners policy and may include dwelling protection, premises liability and loss-of-rental-income options.
Coverage Built Around Your Home
Two homes with similar market values may have very different insurance needs. Construction materials, square footage, roof type, location, wildfire exposure, renovations and local rebuilding costs can all affect coverage availability and pricing.
Caspian Coverage Insurance Services can help you review:
✓ Estimated rebuilding cost instead of relying on market value alone
✓ Available deductibles, limits and coverage options
✓ Additional protection for jewelry, water backup, equipment breakdown or increased liability when available
✓ Insurance options for wildfire exposed or difficult to place properties
Rebuilding Cost Is Not the Same as Market Value
Your home’s market value includes factors such as the land, neighborhood, schools and local real estate demand. Homeowners insurance generally focuses on the estimated cost to repair or rebuild the structure after a covered loss.
Construction costs can change over time. Labor, materials, debris removal, permits and updated building code requirements may make rebuilding more expensive than expected. Review your dwelling limit after major renovations and periodically with your insurance agent to help keep the policy aligned with the home.
Home Insurance for California Wildfire Areas
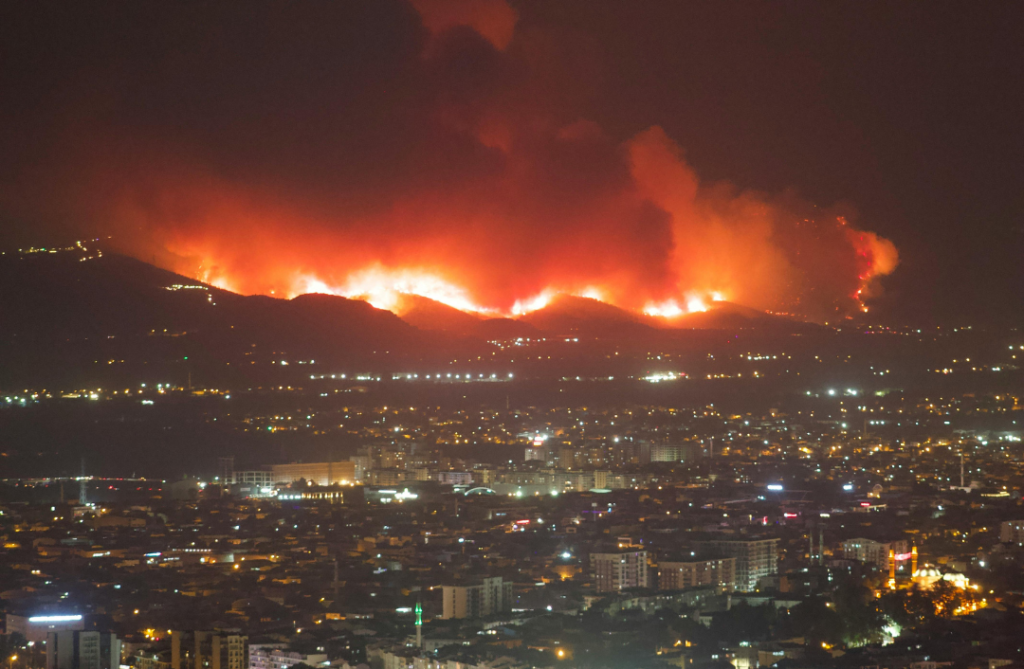
Properties near brush, hillsides, canyons or areas with significant wildfire exposure may have fewer insurance options or additional underwriting requirements. Insurance companies may evaluate the home’s location, roof, surrounding vegetation, construction features, claims history and available fire protection.
When comprehensive coverage is not reasonably available through the traditional insurance market, the California FAIR Plan may provide basic fire insurance as an insurer of last resort. However, a FAIR Plan policy is not the same as a comprehensive homeowners policy. A separate Difference in Conditions or DIC policy may be used to provide certain additional protections, such as theft, water damage and liability coverage.
FAIR Plan and DIC policies are separate contracts. Their limits, deductibles and exclusions should be reviewed together to identify possible gaps.
Having difficulty insuring a California home? Contact us to discuss the options that may be available for your property.
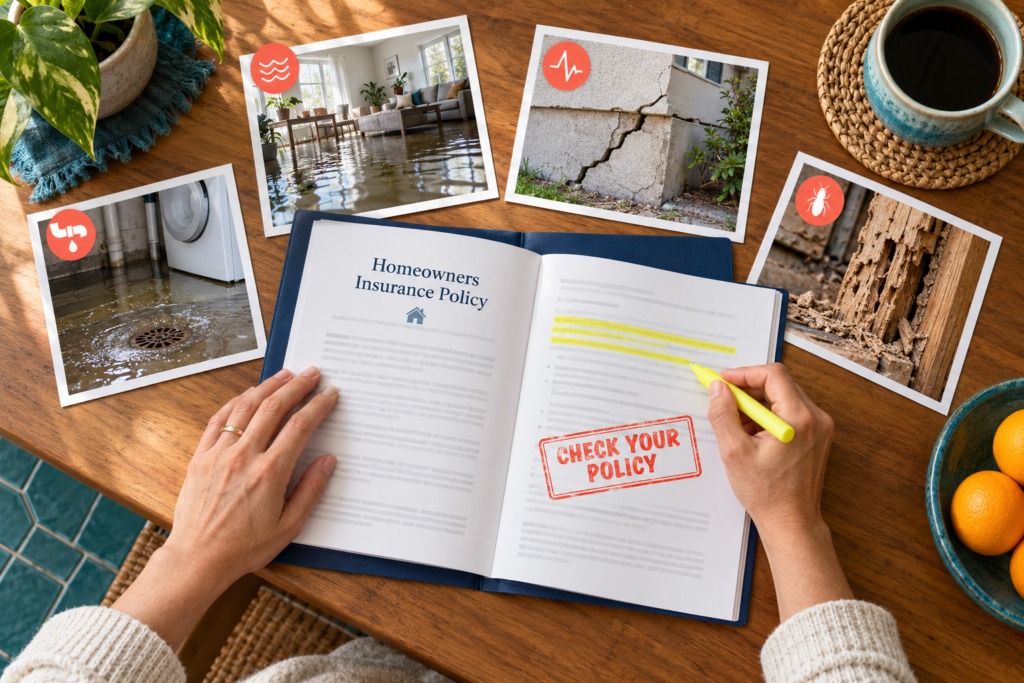
What Is Usually Not Covered by Standard Homeowners Insurance?
Homeowners insurance does not cover every type of damage. Important exclusions and limitations may include:
Earthquake Damage
Most standard homeowners policies do not cover damage caused by earthquake movement. Separate earthquake insurance is generally needed.
Flood Damage
Standard homeowners insurance generally does not cover flooding from rising surface water. Flood insurance can be purchased separately through the National Flood Insurance Program or, when available, a private flood insurance company.
Wear, Deterioration and Maintenance
Home insurance is not a maintenance plan. Damage caused by ordinary wear, neglect, deterioration, pests or long term maintenance problems is generally excluded.
Limited Coverage for Valuable Property
Jewelry, fine art, collectibles, firearms and certain other property may have special limits. Additional scheduled coverage may be appropriate for valuable items.
Every policy is different. Review the policy language, declarations, endorsements and exclusions to understand what is and is not covered.